


Preparing for an accounts payable interview? Whether you are applying for an Accounts Payable Executive, AP Processor, Accounts Payable Specialist or Finance Operations role, interviewers may assess your accounting fundamentals, invoice-processing knowledge, payment controls and ability to resolve vendor-related issues.
This article covers 60 accounts payable interview questions and answers, from basic accounting concepts to purchase orders, three-way matching, the procure-to-pay (P2P) cycle, general ledger coding, vendor reconciliation, payment processing and practical workplace scenarios.
The answers explain the concepts and processes candidates should understand. For questions about your own work experience, use genuine examples from your previous roles, internships or relevant training rather than memorising experiences you have not had.
Key Highlights
- Questions covered: 60 accounts payable interview questions with explanations, practical examples and sample answers.
- Suitable roles: AP Processor, Accounts Payable Executive, AP Specialist and Finance Operations positions.
- Accounting fundamentals: Liabilities, debit and credit entries, working capital and general ledger classification.
- Invoice processing: PO and non-PO invoices, three-way matching, GRN and the procure-to-pay cycle.
- Advanced topics: Vendor reconciliation, ERP systems, payment controls, tax compliance and fraud prevention.
- Interview preparation: Technical questions, workplace scenarios, HR answers and practical preparation tips.
Basic Accounts Payable Interview Questions and Answers
1. What is meant by accounts payable?
Answer: Accounts payable (AP) refers to amounts a business owes suppliers or vendors for goods and services purchased on credit. These unpaid obligations are generally recorded as current liabilities on the balance sheet when payment is expected within the normal operating cycle or the applicable short-term period.
For example, if a company purchases office supplies worth ₹50,000 on credit and has not yet paid the supplier, the outstanding amount may be recorded under accounts payable.
Accounts payable is not itself an expense category. The related purchase may be recorded as an expense, inventory or another asset, depending on its nature and the applicable accounting treatment.
2. When is an accounts payable amount paid?
Answer: An accounts payable balance is normally settled according to the agreed payment terms, invoice due date and the company’s payment-approval procedures. There is no universal rule that every payable must be paid in the following month or financial year.
For example, an invoice dated 1 October with net 30 payment terms is generally due 30 days after the date specified as the starting point under those terms. Some suppliers may require advance payment, while others allow longer credit periods.
An AP professional should verify the due date, supporting documents, payment authorisation and applicable discounts before scheduling payment. The liability remains outstanding until it is settled or otherwise validly cleared.
3. What is working capital, and how does accounts payable affect it?
Answer: Working capital is generally calculated as current assets minus current liabilities. It helps indicate a company’s short-term financial position.
Accounts payable is generally classified as a current liability. An increase in accounts payable reduces working capital if current assets and other liabilities remain unchanged. However, the effect of a transaction depends on the corresponding accounting entry. For example, purchasing inventory on credit may increase both inventory and accounts payable by the same amount, leaving net working capital unchanged at initial recognition. Cash flow and working capital should therefore be analysed separately.
For example, if a company has current assets of ₹10 lakh and current liabilities of ₹6 lakh, its working capital is ₹4 lakh.
Interview tip: Explain how supplier payment terms affect liquidity, working capital and vendor relationships, rather than treating delayed payments as automatically beneficial.
4. What is the difference between accounts payable and accounts receivable?
Answer: Accounts payable and accounts receivable represent opposite sides of credit transactions.
| Feature | Accounts Payable (AP) | Accounts Receivable (AR) |
|---|---|---|
| Meaning | Money the business owes suppliers | Money customers owe the business |
| Balance-sheet classification | Generally a current liability | Generally a current asset |
| Transaction example | Purchasing materials on supplier credit | Selling goods to a customer on credit |
| Main operational focus | Invoice verification and outgoing payments | Customer invoicing and incoming collections |
| Typical balance | Credit | Debit |
For example, when a business purchases inventory on credit, it may recognise a payable to the supplier. When it sells goods to a customer on credit, it may recognise a receivable from that customer.
Important: Accounts payable is not automatically a loss, and accounts receivable is not the same as cash already received.
5. Who are the consignor and consignee in a consignment transaction?
Answer: In a consignment arrangement, the consignor sends goods to another party, known as the consignee, who holds or sells the goods on the consignor’s behalf under the agreed terms.
The consignor generally retains ownership of the consigned goods until the conditions for transferring ownership are met. The consignee does not automatically become the owner simply by receiving the goods.
For accounts payable purposes, it is important to distinguish goods received under a consignment agreement from an ordinary credit purchase. The receipt of consignment stock does not necessarily create an immediate purchase liability for the consignee.
6. What expenses can a seller incur while purchasing, storing and delivering goods?
Answer: A seller or supplier may incur several costs depending on the nature of the business and its contractual responsibilities. These can include:
- Procurement costs: Costs associated with purchasing materials or inventory.
- Storage and warehousing: Expenses related to holding goods before sale or dispatch.
- Packaging and handling: Costs of preparing goods for transportation.
- Transportation and delivery: Freight and logistics costs, depending on contractual delivery terms.
- Insurance: Coverage where required during storage or transit.
- Sales and marketing: Advertising or promotional expenses where relevant.
Not every seller bears every cost. Responsibility for freight, insurance and related charges can depend on the purchase agreement and applicable delivery terms.
Accounts payable relevance: AP staff must understand whether transportation, handling or other charges are correctly billed under the supplier agreement and supported by appropriate documentation.
7. What are the different types of accounting?
Answer: Accounting includes several specialised areas serving different financial and operational purposes.
- Financial accounting: Records and reports financial transactions for general-purpose financial statements.
- Management accounting: Provides financial and operational information for internal business decisions.
- Cost accounting: Analyses costs associated with products, services and business operations.
- Tax accounting: Focuses on tax calculations, reporting and compliance with applicable tax laws.
- Auditing: Involves examining financial information, processes and controls to support assurance or internal oversight.
- Forensic accounting: Applies accounting and investigative techniques to examine suspected fraud or financial disputes.
Accounts payable is primarily a finance and accounting function that supports accurate liability recording, payment processing and financial reporting.
8. What is an invoice, and why is an invoice number important?
Answer: An invoice is a commercial document issued by a supplier requesting payment for goods or services supplied, subject to the agreed transaction terms.
An invoice typically includes the following information:
- Supplier and customer details
- Invoice number and invoice date
- Description, quantity and price of goods or services
- Applicable taxes and other charges
- Total invoice amount and currency
- Payment terms and due date
- Purchase order reference, where applicable
The invoice number helps distinguish transactions, track payments, reconcile supplier statements and detect potential duplicate invoices. In India, additional particulars may be required for a valid GST tax invoice, depending on the transaction and applicable rules.
Example: If a supplier submits invoice INV-1045 twice, the accounts payable system should flag the potential duplication using invoice identifiers and other relevant vendor details before payment is released.
9. What is the accounts payable process?
Answer: The accounts payable process covers the receipt, verification, recording, approval and settlement of supplier invoices.
- Receive the invoice: Capture the supplier invoice through an approved channel.
- Validate invoice details: Check the supplier, invoice number, amount, taxes and supporting documents.
- Match supporting records: Compare the invoice with the purchase order and goods receipt where applicable.
- Resolve discrepancies: Investigate differences in quantities, rates, tax treatment or supplier information.
- Obtain approval: Follow the company’s authorised approval workflow.
- Record the liability: Post the transaction to the appropriate supplier and general ledger accounts.
- Schedule and execute payment: Apply contractual due dates and payment controls.
- Reconcile and retain records: Confirm settlement, resolve outstanding differences and maintain an audit trail.
Depending on the organisation, purchasing, goods receipt, approvals and accounting entries may be handled across different teams or automated systems.
10. What is the role of accounts receivable?
Answer: The accounts receivable (AR) function helps manage amounts customers owe the business for credit sales of goods or services.
Its responsibilities may include generating customer invoices, recording receivables, monitoring due dates, following up on overdue balances, applying incoming payments and reconciling customer accounts.
For example, if a customer receives an invoice for ₹75,000 with a 30-day payment term, the AR team monitors that receivable until payment or other valid settlement occurs.
Interview tip: Remember that accounts payable manages outgoing supplier obligations, while accounts receivable manages incoming customer collections. Both functions support cash flow management and accurate financial records.
Accounts Payable Processor Interview Questions
11. Who is an accounts payable processor?
Answer: An accounts payable (AP) processor is a finance professional responsible for handling supplier invoices, checking supporting documentation, recording payable transactions and preparing invoices for approval or payment.
Depending on the organisation, an AP processor may report to an AP supervisor, finance manager or shared services team leader. The role commonly involves working with accounting software or enterprise resource planning (ERP) systems.
An AP processor does not necessarily have the authority to approve or release payments. Organisations often separate invoice processing, payment authorisation and payment execution to reduce errors and fraud risks.
12. What are the main responsibilities of an accounts payable processor?
Answer: The primary responsibility of an AP processor is to ensure that supplier invoices are accurately processed according to company procedures and payment terms.
- Invoice capture: Receive and register invoices submitted through approved channels.
- Data verification: Check invoice numbers, supplier details, amounts, taxes and due dates.
- Invoice matching: Compare invoices with purchase orders and goods receipts where applicable.
- GL coding: Assign the appropriate accounting and cost centre information.
- Exception handling: Investigate duplicate invoices, missing documents and quantity or price differences.
- Payment preparation: Process approved invoices for scheduled payment according to organisational controls.
- Record maintenance: Maintain invoice records and supporting documentation for reconciliation and audit purposes.
Interview tip: Explain the difference between preparing an invoice for payment and independently authorising the payment.
13. How do you manage the accounts payable process efficiently?
Answer: Efficient accounts payable management requires accurate invoice data, clear approval responsibilities, effective exception handling and visibility into outstanding payments.
- Centralise invoice receipt: Use approved email channels, supplier portals or invoice-processing systems to reduce missing documents.
- Validate invoice information: Check supplier identity, invoice number, amount, taxes and supporting records before posting.
- Apply matching controls: Use two-way or three-way matching where appropriate.
- Maintain approval workflows: Route invoices to authorised approvers according to transaction type and value.
- Monitor due dates: Track outstanding invoices and prioritise payments according to contractual terms.
- Resolve exceptions: Follow up on price differences, missing receipts and incorrect supplier details.
- Reconcile regularly: Compare supplier statements, AP ledgers and relevant general ledger balances.
Automation can help reduce repetitive work, but payment controls, exception reviews and segregation of duties remain important even in highly automated AP systems.
14. What is a PO invoice in accounts payable?
Answer: A PO invoice is a supplier invoice associated with an approved purchase order (PO). The purchase order generally records the agreed items or services, quantities, prices and other purchasing terms.
For example, a company issues a PO for 100 office chairs at an agreed price of ₹3,000 per chair. When the supplier submits an invoice, the AP team checks whether the invoice agrees with the purchase order and the relevant receiving records.
PO-based processing supports purchase authorisation, invoice matching and expenditure control. An invoice linked to a PO may still require investigation if the price, quantity, tax or other details do not agree with approved records.
15. What is a non-PO invoice?
Answer: A non-PO invoice is an invoice that is not linked to a formal purchase order in the company’s purchasing system.
Common examples may include utility bills, professional service fees, subscriptions, rent or other purchases that an organisation permits through a non-PO approval process.
Non-PO invoices are not automatically unauthorised purchases. They should still be supported by appropriate documentation, GL coding, budget checks and approval from the responsible business owner.
Example: A monthly electricity invoice may be processed without a separate PO if that is permitted under the company’s procurement and payment policies.
16. What is three-way matching in accounts payable?
Answer: Three-way matching is an accounts payable control that compares three documents before an invoice is approved for payment:
- Purchase Order (PO): Records what the organisation authorised the supplier to provide.
- Goods Receipt Note (GRN) or receiving record: Confirms the goods received and the quantities accepted.
- Supplier Invoice: States what the supplier is requesting payment for.
Example: A company orders 100 units at ₹500 each. The supplier invoices 100 units, but the receiving record shows that only 90 units have arrived. The AP team should investigate the difference and apply the organisation’s rules for partial receipts, invoice posting and payment.
Three-way matching helps identify quantity and price discrepancies, unsupported invoices and other payment risks. It does not automatically determine whether every invoice must be paid in full or in instalments.
Interview tip: Be prepared to explain two-way matching as well. It generally compares the purchase order and supplier invoice without using a separate goods receipt as the third matching document.
17. What is the P2P cycle in accounts payable?
Answer: P2P stands for Procure-to-Pay, also called Purchase-to-Pay. It describes the process through which a company requests, purchases, receives, accounts for and pays for goods or services.
A typical P2P cycle includes:
- Identifying a purchasing requirement
- Creating and approving a purchase requisition
- Selecting a supplier and issuing a purchase order
- Receiving goods or confirming service delivery
- Receiving and validating the supplier invoice
- Matching and approving the invoice
- Recording and processing payment
- Reconciling transactions and retaining records
The procurement team generally handles supplier selection and purchasing activities, while the accounts payable function focuses on the financial controls, invoice processing and payment stages. Responsibilities vary by organisation.
18. How does accounts payable invoice processing work?
Answer: Invoice processing begins when a company receives a supplier invoice and ends when the invoice has been appropriately recorded, approved, settled and reconciled.
After receiving an invoice, the AP team normally checks its supplier details, invoice number, amount, tax information and purchasing references. PO invoices are matched with relevant purchasing and receiving records, while non-PO invoices follow the applicable coding and approval process.
Any discrepancies should be investigated before payment. Once the invoice has passed the required checks, it can be posted to the accounting system and scheduled for payment according to the approved terms.
Example: If an invoice quotes a higher price than the approved PO, the processor should investigate the difference with procurement or the supplier rather than changing the PO or invoice amount without authorisation.
19. What is the full form of GRN in accounts payable?
Answer: GRN stands for Goods Receipt Note. It is a document or system record confirming the receipt of goods from a supplier.
A GRN may contain details such as the purchase order reference, supplier, item description, quantities received, date of receipt and any shortages or discrepancies recorded during delivery.
In a three-way matching process, the GRN is compared with the purchase order and supplier invoice to establish whether the billed goods correspond to the goods received.
Important: Service purchases may use service entry sheets or other confirmation records instead of a traditional goods receipt note.
20. What is a GL code in accounts payable?
Answer: GL stands for General Ledger. A GL code identifies an account in the organisation’s chart of accounts and helps classify financial transactions accurately.
In accounts payable, GL coding determines whether an invoice is recorded against the correct expense, asset or other relevant account. An invoice may also need a cost centre, department, project or other accounting dimension.
Example: An approved electricity bill may be assigned to a utilities expense GL account, while a purchase of qualifying computer equipment may be recorded in an appropriate asset account under the applicable accounting policy.
Incorrect GL coding can affect financial reporting, department-level expense analysis and reconciliations. The AP processor should apply the organisation’s chart of accounts and seek clarification for unfamiliar or ambiguous transactions.
Accounts Payable Specialist Interview Questions
21. What does an accounts payable specialist do?
Answer: An accounts payable specialist helps manage the accurate recording and settlement of supplier obligations. The role can include invoice processing, supplier reconciliations, payment scheduling, exception management and support for accounting close activities.
Depending on the organisation, an AP specialist may also review complex invoice discrepancies, support process improvements, assist with audits and monitor compliance with purchasing and payment controls.
Interview tip: Explain the specific responsibilities of the role you are applying for rather than assuming every AP specialist has authority over vendor master data or bank payments.
22. What is the difference between accounts payable and an accounts payable specialist?
Answer: Accounts payable is an accounting function and a balance-sheet liability category, whereas an accounts payable specialist is a professional who performs activities within the AP function.
An AP processor may focus primarily on receiving, checking and posting invoices. An AP specialist may have broader responsibilities involving vendor reconciliations, complex exceptions, reporting or process controls, depending on the employer.
The distinction between job titles is not universal. Some organisations use AP Executive, AP Associate, AP Processor and AP Specialist for overlapping responsibilities.
23. What skills are important for an accounts payable specialist?
Answer: An accounts payable specialist needs a combination of accounting knowledge, process discipline, software proficiency and communication skills.
- Accounting fundamentals: Understanding liabilities, debits and credits, accruals and the general ledger.
- Attention to detail: Identifying incorrect invoice amounts, duplicate references and missing information.
- Invoice processing: Knowledge of PO matching, non-PO approvals and payment workflows.
- Spreadsheet proficiency: Using Excel for reconciliation, analysis and reporting.
- ERP knowledge: Familiarity with systems such as SAP, Oracle or other accounting platforms used by the employer.
- Communication: Resolving supplier inquiries and coordinating with procurement, finance and business approvers.
- Confidentiality and integrity: Protecting sensitive financial information and following payment controls.
- Time management: Managing invoice volumes, approval delays and payment deadlines.
Interview tip: Support these skills with examples, such as identifying a duplicate invoice, resolving a supplier statement difference or improving an invoice-tracking process.
24. What qualifications are required for an accounts payable specialist?
Answer: Qualifications depend on the employer, role level and responsibilities. Many accounts payable vacancies prefer candidates with an educational background in commerce, accounting, finance or business administration, although some entry-level roles may accept other qualifications combined with relevant skills.
| Requirement | What Employers May Look For |
|---|---|
| Education | A relevant degree or diploma, such as B.Com, BBA or an accounting-related qualification, depending on the role |
| Accounting knowledge | Understanding of AP, ledger entries, reconciliations, accruals and payment processes |
| Software proficiency | Experience with spreadsheets, accounting software or ERP systems |
| Work experience | Varies from entry-level opportunities to positions requiring prior AP or finance operations experience |
| Process knowledge | Invoice verification, P2P, three-way matching, approvals and supplier reconciliation |
| Communication | Ability to handle vendor queries and coordinate with internal departments |
| Controls and compliance | Awareness of approval procedures, financial controls and applicable tax requirements |
There is no single degree, experience requirement or certification that applies to every accounts payable specialist role. Applicants should review the job description to identify the required qualifications and ERP expertise.
25. Why is invoice verification important in accounts payable?
Answer: Invoice verification helps ensure that payments are made to the correct supplier, for valid business transactions, in the correct amount and according to approved terms.
Verification generally includes checking supplier information, invoice identifiers, prices, quantities, taxes, payment terms and relevant supporting documentation.
Example: If an invoice bank account differs from the supplier’s approved payment details, the processor should follow the organisation’s independent verification and vendor-change controls rather than immediately using the new details.
This process supports accurate accounting, reduces duplicate-payment risk and helps detect errors or potentially fraudulent changes.
26. What are the stages of the full-cycle accounts payable process?
Answer: Full-cycle accounts payable covers the activities needed to process supplier obligations from invoice receipt through settlement and reconciliation.
- Receive and capture the supplier invoice.
- Validate supplier and invoice information.
- Match the invoice to purchasing and receiving records where applicable.
- Assign appropriate GL accounts and other accounting dimensions.
- Resolve discrepancies and obtain required approvals.
- Record the payable in the accounting system.
- Schedule and execute the authorised payment.
- Reconcile supplier balances and retain supporting records.
Full-cycle AP also involves checking that transactions are recorded in the correct accounting period, outstanding liabilities are reconciled and payment records are retained for audit. For example, goods received before month-end may require an accrual or goods-received-not-invoiced (GRNI) entry if the supplier invoice has not yet arrived. In larger organisations, procurement, AP, treasury and general accounting teams may handle different stages of this process.
27. Why is accounts payable not treated as an expense?
Answer: Accounts payable represents an amount owed to a supplier, so it is recorded as a liability. The expense or asset associated with the purchase is recognised separately according to the nature of the transaction and the applicable accounting rules.
Example: A company receives an approved office electricity bill for ₹10,000 on credit. Ignoring taxes and other adjustments, the initial accounting entry may be:
| Account | Debit | Credit |
|---|---|---|
| Electricity Expense | ₹10,000 | — |
| Accounts Payable | — | ₹10,000 |
When the company subsequently pays the supplier, the payable liability is reduced and the bank balance decreases. The payment itself does not automatically create a second electricity expense.
If the purchase involves inventory or a qualifying fixed asset, the initial debit may instead be recorded in an appropriate asset account.
28. What is SOX in accounting, and how does it relate to accounts payable?
Answer: SOX stands for the Sarbanes-Oxley Act of 2002, a United States law covering areas of corporate governance, financial reporting and internal controls for entities within its scope.
For applicable organisations, SOX-related financial controls may involve segregation of duties, documented authorisations, access restrictions, reconciliations and evidence supporting financial transactions.
In accounts payable, relevant internal controls may include:
- Restricting who can create or change supplier records.
- Separating payment preparation from payment approval.
- Maintaining supporting documents and approval records.
- Reconciling outstanding AP balances with the general ledger.
- Reviewing exceptions and suspicious transactions.
Important: SOX is a US law and does not automatically apply to every business in India. Its relevance depends on the organisation and applicable regulatory requirements.
29. What are the different types of assets in accounting?
Answer: Assets are economic resources controlled by an entity as a result of past events. They can be classified in different ways depending on the purpose of the financial statement or analysis.
Classification by liquidity:
- Current assets: Examples include cash, trade receivables and inventory, subject to the applicable classification criteria.
- Non-current assets: Examples include property, plant and equipment, long-term investments and certain intangible assets.
Classification by physical form:
- Tangible assets: Physical resources such as machinery, buildings and equipment.
- Intangible assets: Identifiable non-physical resources, such as certain software rights, patents and licences.
These are different classification methods. For example, an asset can be both tangible and non-current.
Accounts payable relevance: AP staff should recognise that supplier invoices may relate to expenses, inventory or capital assets and must be coded according to the company’s accounting policies.
30. What are the normal debit and credit balances of accounts receivable and accounts payable?
Answer: Accounts receivable normally has a debit balance because it is an asset account. Accounts payable normally has a credit balance because it is a liability account.
However, debit and credit describe accounting entries or account balances, not alternative names for receivables and payables.
| Account | Normal Balance | Typical Increase | Typical Decrease |
|---|---|---|---|
| Accounts Receivable | Debit | Debit | Credit |
| Accounts Payable | Credit | Credit | Debit |
Example 1: When a company makes a credit sale, it generally debits accounts receivable and credits the appropriate revenue account, subject to applicable taxes and accounting requirements.
Example 2: When a company pays an existing supplier liability, it generally debits accounts payable and credits the bank account.
Interview tip: Be prepared to explain why liabilities usually increase through credit entries, while assets usually increase through debit entries.
Technical Accounts Payable Interview Questions and Answers
These technical accounts payable interview questions assess your understanding of invoice processing, supplier payments, financial controls, ERP systems, reconciliation and common workplace scenarios. For experience-based questions, adapt the suggested approach to work you have actually performed.
31. What is the difference between billable and non-billable expenses?
Answer: Billable expenses are costs that a business is entitled to charge to a customer under an agreement. Non-billable expenses are costs that the business bears without separately recovering them from a customer.
For example, a consulting company may incur approved travel expenses that it can recharge to a client. These are billable expenses if the contract permits reimbursement. The company’s general office administration expenses may be non-billable.
In accounts payable, the team must still verify and record the supplier invoice correctly, whether the expense is billable or non-billable. The distinction also matters for project accounting, cost allocation and customer billing.
Interview tip: Do not confuse billable expenses with accounts payable. A supplier invoice creates a potential payment obligation, while billability determines whether the business can recover a related cost from a customer.
32. How do you calculate total liabilities on a balance sheet?
Answer: Total liabilities represent the company’s recognised financial obligations at the reporting date. They generally include current liabilities and non-current liabilities.
Formula: Total Liabilities = Current Liabilities + Non-Current Liabilities.
| Liability | Illustrative Amount |
|---|---|
| Accounts payable | ₹2,00,000 |
| Accrued expenses | ₹50,000 |
| Short-term borrowings | ₹1,50,000 |
| Long-term borrowings | ₹6,00,000 |
| Total liabilities | ₹10,00,000 |
This example assumes each amount is a separate recognised liability and there is no overlap between categories.
The accounting equation is Assets = Liabilities + Equity. Accounts payable normally forms part of current liabilities, subject to the applicable classification requirements.
33. What are the essential components of a supplier invoice?
Answer: A supplier invoice should contain sufficient information to identify the transaction, calculate the amount payable and support accounting and tax compliance.
- Supplier details: Name, address and relevant tax registration details.
- Customer details: Name, address and relevant registration information.
- Invoice reference: Invoice number and issue date.
- Transaction details: Description of goods or services, quantities, units and prices.
- Tax details: Applicable tax rates, taxable values and tax amounts.
- Payment information: Total amount, currency, due date and payment terms.
- Supporting references: Purchase order or contract number where applicable.
For Indian GST invoices, additional particulars may be required under the applicable GST rules, depending on the supplier and transaction. AP teams should follow the relevant statutory and internal validation requirements.
Interview tip: Explain how you would respond if an invoice is missing a required tax detail, contains an incorrect supplier name or duplicates an existing invoice number.
34. What is a debit note in accounts payable?
Answer: A debit note is a document used to communicate a debit adjustment or claim against another party. In accounts payable, a buyer may issue a debit note when requesting a reduction in the amount owed to a supplier, for example because of returned goods, damaged items or an overcharge.
Example: A company receives goods invoiced at ₹50,000 but subsequently identifies an agreed adjustment of ₹5,000 for damaged items. The buyer may raise a debit note for ₹5,000, while the supplier may issue a corresponding credit note. The adjustment should follow the agreed commercial process and applicable accounting and tax requirements.
Important distinction: Debit notes and credit notes can have specific meanings under tax law. In India, GST debit notes and credit notes issued by suppliers are governed by statutory requirements and should not be confused with every buyer-issued commercial debit note.
Interview tip: Explain how the adjustment affects the outstanding supplier balance and why supporting documentation and authorisation are necessary.
35. How do you ensure accuracy when processing invoices and payments?
Answer: Accurate invoice processing requires consistent validation, clear approval controls and proper reconciliation.
- Verify supplier information: Confirm that the supplier is recorded and authorised in the vendor master.
- Check invoice details: Validate the invoice number, date, quantities, prices, taxes and total amount.
- Match supporting records: Compare the invoice against an approved PO and goods receipt where applicable.
- Identify duplicates: Check for repeated invoice numbers, amounts or other suspicious combinations.
- Obtain approval: Follow the company’s authorised approval workflow.
- Confirm payment details: Apply independent verification controls for new or changed bank account information.
- Reconcile: Review supplier balances, payment records and the general ledger.
Example: If a supplier submits two invoices with different numbers but identical amounts and supporting details, the AP team should investigate whether they represent separate transactions or a duplicate billing attempt.
36. What is the difference between two-way and three-way matching in accounts payable?
Answer: Two-way and three-way matching are invoice verification controls used to compare supplier invoices with approved purchasing and receiving information.
| Feature | Two-Way Matching | Three-Way Matching |
|---|---|---|
| Documents compared | Purchase order and supplier invoice | Purchase order, receiving record and supplier invoice |
| Main verification | Checks agreement with authorised purchase details | Also checks goods received or accepted |
| Common use | Transactions where receipt confirmation is not part of the matching requirement | Goods purchases requiring receipt verification before payment |
| Possible exception | Invoice price differs from the PO | Invoice quantity exceeds the quantity received |
Example: A purchase order authorises 100 units at ₹200 each. If the supplier invoices 100 units at the agreed price, the documents may pass two-way matching. Under three-way matching, the receiving record is also checked. If only 80 units were received, the invoice may require investigation or an approved partial-processing arrangement.
The matching method depends on the transaction, ERP configuration and company policy. Service purchases may use service confirmation records instead of a traditional goods receipt.
37. How do you handle discrepancies between purchase orders, invoices and receipts?
Answer: I would first identify the type of discrepancy and then follow the company’s exception-resolution process before approving the affected invoice for payment.
Common discrepancies include:
- Invoice price differs from the approved PO price.
- Invoice quantity exceeds the quantity received.
- The goods receipt has not yet been recorded.
- The invoice contains incorrect taxes or additional charges.
- The PO is closed, cancelled or references the wrong supplier.
Resolution approach: Review the documents, confirm the discrepancy, contact procurement, the receiving team or the supplier, and obtain an authorised correction or supporting explanation. Where permitted, the organisation may process an approved partial invoice or apply an established tolerance.
Important: An AP processor should not independently amend supplier invoices, receiving quantities or authorised purchase prices merely to clear a system exception.
38. How do you reconcile the accounts payable subledger with the general ledger?
Answer: Accounts payable subledger reconciliation involves comparing the detailed supplier balances recorded in the AP system with the corresponding general ledger control account. The objective is to identify differences and ensure that the reported liability is complete and accurate.
Typical reconciliation steps:
- Obtain the accounts payable subledger report and the relevant general ledger balance for the same reporting date.
- Confirm that both reports cover the same company, accounting period and currency basis.
- Compare the total supplier balances with the general ledger control account.
- Investigate differences caused by posting errors, timing differences, manual journals or transactions not transferred between systems.
- Document the reconciliation and process any authorised correcting entries.
- Retain supporting records and obtain the required review or approval.
Example: If the AP subledger shows ₹8,00,000 payable but the general ledger control account shows ₹7,80,000, the ₹20,000 difference must be investigated. The team should not post an adjustment simply to force both figures to agree without identifying the cause.
Interview tip: Explain why subledger reconciliation is important during month-end closing and how you would investigate an unexpected debit balance or an unposted invoice.
39. How do you handle vendor enquiries and resolve payment issues?
Answer: Vendor enquiries should be handled by checking the supplier’s account, identifying the reason for the payment issue and communicating an accurate status without bypassing internal controls.
Recommended process:
- Confirm the supplier’s identity and invoice reference.
- Check whether the invoice has been received, recorded and approved.
- Review the payment terms, due date and payment status.
- Investigate issues such as unmatched invoices, blocked payments or incorrect supplier details.
- Coordinate with procurement, approvers or treasury where necessary.
- Communicate the verified status and document the resolution.
Example: If a supplier reports an overdue invoice, the processor should verify whether it was received and approved, whether the due date has passed, and whether a payment was initiated or returned.
Interview tip: Avoid promising an immediate payment before confirming approval and payment-processing status.
40. How do you optimise the payment cycle and evaluate early payment discounts?
Answer: Payment-cycle management aims to settle valid obligations on time while maintaining appropriate cash flow, supplier relationships and internal controls.
Useful approaches include improving invoice turnaround times, tracking due dates, resolving blocked invoices quickly, scheduling payment runs and reviewing supplier payment terms.
Early payment discount example: A supplier offers payment terms of 2/10 net 30. This generally means the buyer can deduct 2% if it pays within 10 days; otherwise, the full invoice amount is due within 30 days, subject to the contract.
For an eligible ₹1,00,000 invoice, the 2% discount would be ₹2,000, giving a discounted payment of ₹98,000, before considering any tax or contractual adjustments.
Whether to take the discount depends on the company’s liquidity, financing cost, payment policy and the terms of the transaction. AP teams should not accelerate payments without proper approval.
41. How do you maintain compliance with tax regulations and vendor payment terms?
Answer: Maintaining compliance requires correctly processing supplier invoices under applicable tax laws, contractual terms and the organisation’s approval procedures.
In an Indian accounts payable role, relevant checks may include:
- GST: Verify applicable tax invoice particulars and follow the company’s input tax credit validation process.
- TDS: Identify whether tax deduction at source applies and use the correct statutory provisions and rates.
- Payment terms: Monitor due dates and comply with contractual requirements.
- Supplier records: Check required registration, tax and identification details.
- Documentation: Retain invoices, approval evidence and relevant supporting records.
Additional rules may apply to particular supplier categories, transactions and jurisdictions, including certain payments to micro and small enterprises. Applicability and statutory requirements should be checked against current law and company policy.
Interview tip: Demonstrate awareness of GST, TDS and payment compliance without quoting a tax rate or statutory deadline unless you have verified that it applies to the specific transaction.
42. What methods do you use to prevent duplicate payments?
Answer: Duplicate-payment prevention requires a combination of system checks, accurate vendor master data, invoice validation and payment reconciliation.
- Invoice-number validation: Flag repeated supplier invoice references.
- Combination checks: Compare supplier, amount, invoice date and other transaction details.
- Vendor master controls: Identify duplicate supplier records that could allow the same invoice to be processed twice.
- Payment-run review: Check payment proposals for repeated or unusual transactions.
- Segregation of duties: Separate responsibilities for entering invoices, approving payments and releasing funds.
- Reconciliation: Review supplier statements and bank/payment records.
Example: A supplier issues invoice INV-205, but the same invoice is subsequently entered as INV205. A system checking only exact invoice-number matches may not detect the duplication. Additional supplier and amount checks can help identify the risk.
Interview tip: Explain that prevention is preferable to recovering funds after a duplicate payment has already been released.
43. What is accounts payable ageing, and how does it affect cash flow?
Answer: An accounts payable ageing report groups outstanding supplier invoices according to how long they have remained unpaid, commonly measured against their due dates.
Typical ageing categories include:
| Category | Meaning |
|---|---|
| Not yet due | Payment due date has not passed |
| 1–30 days overdue | Payment is up to 30 days past its due date |
| 31–60 days overdue | Payment is 31 to 60 days past its due date |
| 61–90 days overdue | Payment is 61 to 90 days past its due date |
| Over 90 days overdue | Payment is more than 90 days past its due date |
Some companies use ageing from the invoice date rather than the due date, so the basis of the report should always be identified.
Ageing reports help finance teams monitor overdue liabilities, prioritise payment investigations, forecast cash outflows and identify supplier accounts requiring reconciliation.
Interview tip: Explain how you would investigate a supplier balance that remains overdue despite the system showing a completed payment.
44. How do you process employee expense reports and reimbursements?
Answer: Employee reimbursements are processed by verifying that claimed expenses are genuine, business-related, supported and approved under the organisation’s expense policy.
- Receive the expense report and supporting receipts.
- Check the employee, claim dates, amounts and business purpose.
- Review policy limits, eligible expense categories and required approvals.
- Identify duplicate receipts, previous reimbursements or company-card transactions.
- Apply the appropriate accounting and tax treatment.
- Process authorised reimbursement through the approved payment channel.
- Retain records and reconcile the payment.
Example: If an employee submits a hotel receipt already paid using a corporate card, the processor should verify whether a separate reimbursement would duplicate the original payment.
Depending on the organisation, expense processing may be managed by AP, payroll, travel operations or a dedicated expense-management team.
45. How do you maintain accurate vendor master data?
Answer: Vendor master data contains the information an organisation uses to identify suppliers, record transactions and make authorised payments.
Important fields may include the supplier’s legal name, address, tax registration details, approved payment terms and verified bank account information.
Recommended controls:
- Require appropriate documentation before creating a supplier record.
- Check for existing or duplicate supplier accounts.
- Restrict access to vendor creation and modification functions.
- Use independent verification for changes to banking details.
- Maintain approval records and an audit trail of changes.
- Periodically review inactive, incomplete or potentially duplicated records.
Example: A supplier requests that future payments be made to a new bank account. The AP team should apply the company’s supplier-change verification procedure using trusted contact information rather than relying solely on the incoming request.
46. How do you manage vendor relationships and negotiate payment terms?
Answer: Good vendor management requires clear communication, reliable payment information and consistent handling of disputes.
Accounts payable teams can support vendor relationships by responding to invoice enquiries, addressing discrepancies, providing verified payment updates and following approved contractual terms.
Payment-term discussions: Procurement or another authorised team may negotiate credit periods, early-payment discounts, payment methods and dispute procedures. AP contributes payment history, ageing data and operational feedback.
Example: A supplier requests a shorter payment period because of repeated delays. The company may review the approval bottlenecks and contractual obligations before deciding whether to revise the terms.
Interview tip: Do not claim authority to negotiate or change commercial terms unless this genuinely formed part of your role.
47. What is your experience with accounting software and ERP systems for accounts payable?
Suggested answer: Explain which software you have actually used, the tasks you performed and how the system supported the accounts payable workflow.
Common AP activities performed through accounting or ERP software include:
- Creating and validating supplier invoice records.
- Matching purchase orders, goods receipts and invoices.
- Assigning general ledger accounts and cost centres.
- Routing invoices for approval and reviewing exceptions.
- Monitoring vendor balances and payment status.
- Generating ageing, reconciliation and closing reports.
How to frame your answer: Name the accounting or ERP software you have actually used, explain the AP tasks you performed and describe how you handled verification, approvals or discrepancies. Candidates with training-only exposure should clearly describe it as practical learning rather than professional experience.
For example, someone who has practised invoice entry in an accounting software training environment can discuss the steps involved in recording a supplier bill, checking the account classification and reviewing the outstanding balance.
48. What procedures do you follow during month-end or year-end closing in accounts payable?
Answer: Accounts payable closing procedures help ensure that supplier obligations and related expenses or assets are recorded in the correct reporting period.
Common activities include:
- Reviewing unposted or pending supplier invoices.
- Identifying goods or services received but not yet invoiced.
- Supporting accruals and goods-received-not-invoiced (GRNI) reconciliations.
- Reconciling the AP subledger to the general ledger control account.
- Reviewing aged balances, duplicate payments and unusual debit balances.
- Investigating supplier statement differences and unmatched transactions.
- Supporting cut-off checks and retaining audit documentation.
Example: A company receives goods before the financial year-end, but the supplier invoice arrives afterwards. Finance may need to recognise the relevant obligation in the correct reporting period, subject to the applicable accounting requirements.
Interview tip: Distinguish invoice posting from accrual accounting and explain why reconciliation is important for accurate financial statements.
49. How do you prevent and detect fraud in accounts payable?
Answer: Accounts payable fraud risks include fictitious suppliers, unauthorised invoices, altered bank details, duplicate payments and collusion between individuals.
Preventive and detective controls may include:
- Segregation of duties: Separate supplier creation, invoice processing, payment approval and payment release where practical.
- Vendor verification: Check supplier identity and independently validate bank-account changes.
- Invoice matching: Compare payment requests with approved purchasing and receiving records.
- Approval controls: Require appropriate authorisation for invoices and exceptional payments.
- Access controls: Limit sensitive ERP permissions and review system activity.
- Monitoring: Investigate repeated invoices, unusual supplier changes and unexpected payment patterns.
- Reconciliation and audit: Review supplier balances, bank transactions and control exceptions.
Example: An email appearing to come from a supplier asks AP to urgently change payment details. The processor should follow approved verification procedures rather than accepting the request solely because the message uses a familiar supplier name.
Interview tip: Explain the action you would take when identifying a suspicious request, including escalation and preservation of relevant records.
50. Which software tools are commonly used in accounts payable?
Answer: Accounts payable teams use accounting systems, enterprise resource planning software, spreadsheet tools and invoice-automation platforms.
| Tool or Category | Common AP Applications |
|---|---|
| SAP | Supplier invoice posting, purchase-order integration, reporting and payment-related processes |
| Oracle ERP | Invoice processing, supplier management, accounting integration and AP reporting |
| Microsoft Dynamics 365 | Vendor invoices, approvals, supplier balances and financial operations |
| QuickBooks | Recording bills, managing supplier balances and tracking payments |
| Microsoft Excel | Reconciliations, invoice tracking, data analysis and reporting |
| AP automation platforms | Invoice capture, workflow approvals, matching and exception management |
The exact features available depend on the software product, edition, modules, configuration and user permissions.
Interview tip: Be specific about the tools you have used. Basic awareness of SAP is different from experience processing invoices in an SAP production environment.
51. What are the advantages of the purchase order (PO) process?
Answer: A structured purchase order process helps organisations authorise purchases, communicate agreed terms and control spending before receiving supplier invoices.
- Spending control: Purchases can be reviewed against budgets and approval limits.
- Clear requirements: The PO records agreed descriptions, quantities, prices and delivery terms.
- Invoice verification: AP can compare incoming invoices with approved purchasing records.
- Discrepancy identification: Differences in price or quantity can be detected before payment.
- Procurement visibility: Buyers can track outstanding orders and commitments.
- Audit trail: The purchasing and approval history provides evidence supporting the transaction.
Example: If a supplier invoices ₹1,20,000 for goods covered by a PO authorised at ₹1,00,000, the AP team can identify the difference and request clarification.
A PO does not guarantee error-free processing or immediate payment. Invoices may still require receipt confirmation, matching, approval and other checks.
52. What is the difference between PO and non-PO invoice processing?
Answer: The main difference is whether the supplier invoice is linked to a formally approved purchase order. Both PO and non-PO invoices require appropriate verification and authorisation before payment.
| Feature | PO Invoice | Non-PO Invoice |
|---|---|---|
| Purchase order reference | Linked to an approved PO | Not linked to a formal PO |
| Common examples | Inventory, equipment or approved services purchased against a PO | Utilities, rent, subscriptions or other permitted non-PO expenses |
| Invoice verification | May involve two-way or three-way matching | Requires validation against contracts, supporting documents or other evidence |
| Approval process | Follows applicable purchasing, matching and payment controls | Usually requires approval by an authorised business owner or cost centre approver |
| GL coding | May be derived from purchasing records or require validation | Usually requires appropriate expense or asset classification |
| Exception handling | May involve price, quantity, receipt or PO-status differences | May involve missing support, unclear ownership or approval issues |
| Processing time | Depends on matching and exception status | Depends on supporting documents and approvals |
| Risk controls | Purchase authorisation, matching, invoice validation and payment approval | Document validation, budget checks, invoice approval and payment controls |
| Payment release | After applicable approvals and payment checks | After applicable approvals and payment checks |
Example of a PO invoice: A company orders 20 laptops through an approved purchase order. The supplier’s invoice is checked against the agreed price and relevant receipt records.
Example of a non-PO invoice: A company receives a monthly office rent invoice. If the organisation permits non-PO processing, the invoice may be checked against the lease agreement and routed for the required approval.
Important: Non-PO does not mean unapproved, and PO-based invoices are not automatically payable immediately. The actual processing workflow depends on the company’s controls.
53. What are the risks of processing non-PO invoices?
Answer: Non-PO invoices can carry additional processing risks when purchases are not supported by a standard purchase-order approval and matching workflow.
Potential risks include:
- Unclear purchase authorisation: The processor may need to identify who approved the expense.
- Missing documentation: The invoice may lack a contract, service confirmation or other supporting record.
- Incorrect GL coding: Expenses may be charged to the wrong account or cost centre.
- Approval delays: Time may be lost identifying the responsible business owner.
- Duplicate or unsupported payments: Weak invoice validation can increase the risk of incorrect payments.
- Budget control issues: Expenditure may be difficult to track if it bypasses normal purchasing visibility.
How to reduce these risks: Organisations can use documented non-PO policies, clear approval limits, mandatory supporting documents, appropriate GL coding, duplicate-invoice checks and regular reconciliations.
Interview tip: Avoid claiming that all non-PO invoices are improper. Explain how the controls should be proportionate to the transaction and the organisation’s approved procurement process.
Accounts Payable HR Interview Questions and Sample Answers
Along with technical knowledge, employers assess how accounts payable candidates communicate, manage deadlines, resolve problems and work with colleagues and suppliers. These sample answers provide a structure for preparation. Adapt them to your actual qualifications and experience rather than presenting fictional achievements as your own.
54. Why did you choose a career in accounting?
Sample answer: “I am interested in accounting because it combines financial accuracy, problem-solving and an understanding of how businesses operate. Accounts payable particularly interests me because the role involves checking financial transactions, working with suppliers and ensuring that payments are processed correctly. I want to strengthen my accounting and finance operations skills while contributing to reliable financial records.”
What interviewers assess: Your interest in accounting, understanding of the role and reasons for choosing this career path.
For freshers: You can refer to relevant coursework, accounting software training or academic projects. Experienced candidates should connect their answer to responsibilities they have actually handled.
55. How do you manage pressure when there is an urgent payment deadline?
Sample answer: “When a payment deadline is approaching, I would first check the invoice status, payment terms and outstanding approvals. I would prioritise the task according to its urgency and business impact, coordinate with the relevant teams and keep stakeholders informed. I would also ensure that the required checks are completed rather than bypassing payment controls to meet the deadline.”
Practical approach:
- Confirm the payment due date and reason for urgency.
- Check whether the invoice has been validated and approved.
- Identify missing documents or payment-processing exceptions.
- Coordinate with authorised approvers or the payment team.
- Escalate genuine risks through the approved process.
Interview tip: A strong answer demonstrates urgency without suggesting that accuracy, approval or fraud-prevention checks can be ignored.
56. What motivated you to apply for an accounts payable position?
Sample answer: “I applied for this accounts payable position because it matches my interest in accounting operations, invoice processing and financial accuracy. I would like to develop my knowledge of supplier payments, reconciliations and ERP-based workflows. I am also interested in contributing to an organised finance team where accurate transactions and timely communication are important.”
How to improve your answer: Review the job description and identify two or three responsibilities that genuinely match your background. These may include invoice processing, Excel reporting, reconciliation, vendor communication or familiarity with accounting software.
Avoid generic statements such as wanting to join the company only because it is well known. Explain why the responsibilities and opportunities of the position interest you.
57. How would you handle a complex or urgent supplier payment request?
Sample answer: “I would begin by understanding the payment request and checking the supporting invoice, approval status and due date. If there were discrepancies or missing information, I would contact the relevant team to resolve them. For a time-sensitive request, I would escalate the matter through the approved process while ensuring that supplier verification and payment authorisation requirements were followed.”
Illustrative scenario: A supplier contacts the company requesting immediate payment to prevent a disruption in delivery. The invoice is valid, but the required business approval is still pending.
An appropriate response would involve confirming the invoice details, contacting the authorised approver, explaining the urgency and recording the status. The processor should not independently release payment without the necessary authorisation.
Interview tip: For an experience-based interview, describe a genuine example using the situation, action and result. If you have not encountered such a case, explain how you would approach it rather than claiming that you have.
58. What are your strengths and weaknesses?
Answer: For an accounts payable interview, choose strengths that match the responsibilities of the role and describe a genuine area where you are working to improve.
Sample strengths answer: “One of my strengths is attention to detail. I prefer to verify information carefully, particularly when working with invoice amounts, supporting documents or financial records. I am also organised and comfortable following structured processes to complete tasks accurately.”
Sample weakness answer: “Earlier, I sometimes spent too much time reviewing straightforward tasks because I wanted to avoid mistakes. I am working on becoming more efficient by using checklists, identifying high-risk items and setting appropriate time limits while maintaining accuracy.”
Interview tip: Do not claim that you never make mistakes or always meet every deadline. A credible answer describes real strengths, acknowledges limitations and explains how you work on them.
59. How do you explain complex accounting issues to colleagues or suppliers?
Sample answer: “I would first understand the other person’s concern and determine how much technical information they need. I would explain the issue using clear language, relevant invoice or transaction details and the steps needed for resolution. I would also invite questions and confirm that we agree on the next action.”
Example: A supplier asks why an invoice has not been paid. The issue is that the billed quantity does not match the goods receipt.
Instead of only saying that the invoice has failed three-way matching, the AP processor could explain that the company’s records show a difference between the number of items received and the quantity billed. They could then identify which team is reviewing the difference and what information is required.
Interview tip: Demonstrate that effective communication involves accuracy, clarity and realistic expectations. Avoid sharing confidential financial information with unauthorised parties.
60. Do you have any questions for us?
Answer: Yes. Asking relevant questions helps candidates understand the role, team responsibilities and the company’s accounts payable processes.
Useful questions to ask an interviewer:
- Which accounting or ERP systems does the accounts payable team use?
- Does this role focus mainly on PO invoices, non-PO invoices or both?
- How are invoice discrepancies and supplier escalations usually handled?
- What are the main performance expectations for someone joining this position?
- How does the AP team coordinate with procurement, treasury and general accounting?
- Are there opportunities to learn automation or participate in process improvement projects?
Select two or three questions that are relevant to the discussion. Avoid asking questions that the interviewer has already answered.
How to Prepare for an Accounts Payable Interview
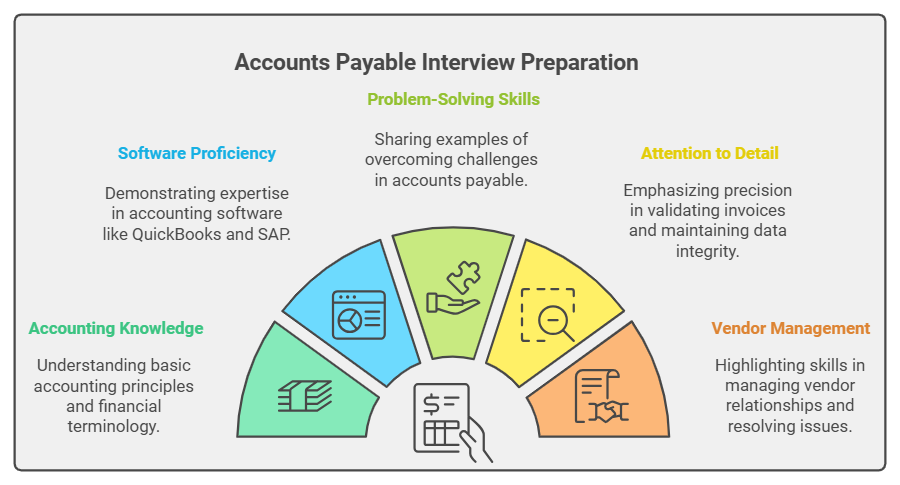
Accounts payable interview preparation should combine accounting fundamentals with practical knowledge of invoice processing, payment controls and supplier communication. These seven areas can help candidates prepare for both technical and HR interview rounds.
1. Revise Accounting Fundamentals
Review debits and credits, assets and liabilities, accrual accounting, journal entries and the chart of accounts. Be prepared to explain how supplier invoices affect accounts payable and why payments reduce outstanding liabilities.
Practise simple accounting entries for credit purchases, expense invoices and supplier payments. Interviewers may ask you to explain the entry rather than merely repeat a definition.
2. Understand Accounts Payable Software
Learn how accounting systems support invoice entry, supplier records, purchase-order matching, approvals, payment processing and reporting.
Common tools include SAP, Oracle ERP, Microsoft Dynamics, QuickBooks and Microsoft Excel. You do not need to claim experience with every platform. Focus on the tools required by the vacancy and explain what you can genuinely use.
3. Practise Solving Invoice Discrepancies
Prepare for scenarios involving incorrect prices, missing purchase orders, duplicate invoices, unmatched goods receipts and overdue supplier payments.
For each scenario, explain how you would identify the problem, verify the supporting documents, contact the appropriate team and resolve the issue through the approved process.
4. Demonstrate Attention to Detail
Accounts payable roles require accuracy when checking invoice numbers, supplier identities, amounts, tax details, due dates and banking information.
Prepare a real example from work, training or an academic activity that shows how you checked information, identified an error or improved the quality of a task. Avoid exaggerating the financial impact of your contribution.
5. Prepare for Vendor Communication Questions
Interviewers may ask how you would respond to a supplier requesting payment, disputing an invoice or reporting incorrect payment information.
Practise explaining invoice status clearly, documenting enquiries and escalating issues when required. Good supplier communication involves professionalism without making promises that the AP team cannot authorise.
6. Improve Organisation and Deadline Management
Accounts payable teams often work with multiple invoices, approval queues, supplier enquiries and payment deadlines.
Be prepared to discuss how you prioritise tasks, use checklists or tracking reports, manage exceptions and communicate delays. Explain how you maintain control when several urgent requests arrive at once.
7. Understand Accounts Payable Process Improvements
Employers may value candidates who can identify unnecessary manual work, recurring errors and delays in the invoice-to-payment process.
Examples of improvement opportunities include standardising invoice submissions, reducing duplicate entries, improving exception tracking and using appropriate workflow automation.
When discussing improvements, explain how you would measure their effectiveness through indicators such as processing time, error rates, overdue invoices or reconciliation differences. Use actual results only when you can substantiate them.
Conclusion
These 60 accounts payable interview questions and answers cover accounting fundamentals, invoice processing, purchase orders, three-way matching, the procure-to-pay cycle, supplier management, financial controls and common workplace scenarios.
For technical questions, focus on understanding the accounting logic and explaining the steps involved in an AP process. For HR and experience-based questions, prepare genuine examples that demonstrate accuracy, communication, problem-solving and responsible handling of financial transactions.
Before your interview, review the employer’s job description, required accounting systems and the responsibilities of the specific accounts payable position. This will help you tailor your preparation to the role.
FAQs
Common accounts payable interview questions cover invoice processing, accounts payable versus receivable, PO and non-PO invoices, three-way matching, the P2P cycle, GL coding, payment approvals, duplicate-payment prevention and supplier reconciliation. Experienced candidates may also be asked about ERP systems and month-end closing.
Review accounting fundamentals, invoice verification, purchase orders, payment terms, vendor reconciliation and financial controls. Practise explaining journal entries and real workplace scenarios. Check which accounting software the employer uses and prepare genuine examples that demonstrate accuracy and problem-solving.
Important accounts payable skills include accounting knowledge, attention to detail, invoice processing, spreadsheet proficiency, ERP familiarity, organisation, supplier communication and problem-solving. Understanding approval workflows and payment controls is also valuable. Requirements vary according to the employer and role level.
Accuracy helps ensure that valid supplier invoices are recorded and paid correctly. It reduces the risk of duplicate payments, incorrect GL coding, tax errors and reconciliation differences. Reliable invoice records also support financial reporting, audit trails and supplier relationships.
Accounts payable teams may use SAP, Oracle ERP, Microsoft Dynamics, QuickBooks, Excel and specialised AP automation platforms. These tools support invoice recording, approvals, supplier account management, reconciliation and reporting. The exact software depends on the organisation.

 Beware of Scammers
